Can You Get Equipment Financing After Bankruptcy, With No Credit Score, or as a Brand-New Business?
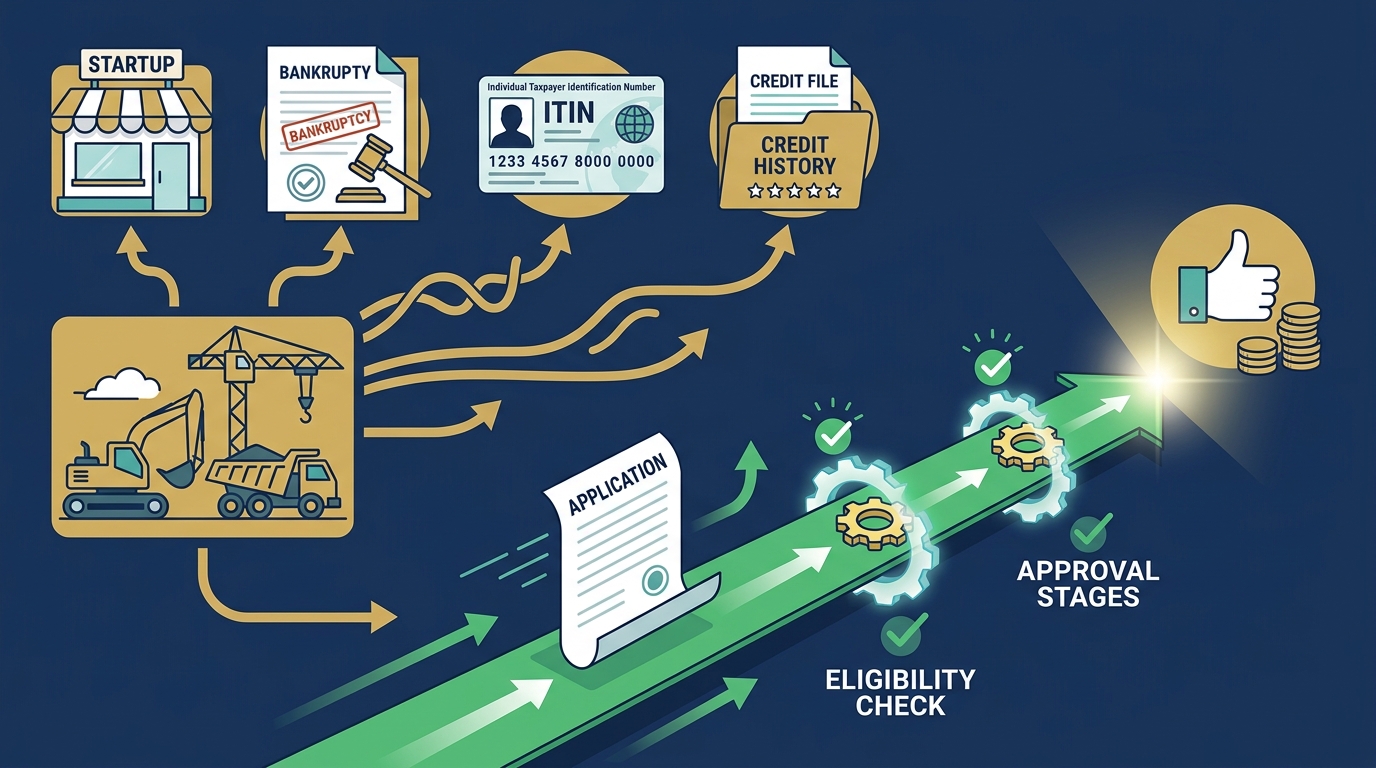
Quick Summary: Programs may exist for applicants with past bankruptcy, challenged credit, thin or no credit, ITIN-only status, and even day-one startups. The Funding Booth helps business owners explore equipment-financing options with a soft inquiry, so checking available paths does not require a hard credit pull. Every file is different, and approval, terms, down payment, and documentation depend on the applicant, equipment, and lender guidelines.
A bank decline can feel personal, especially when the equipment is central to the work you are ready to do. At The Funding Booth, we see credit history as one part of a larger business story—not a reason to stop asking questions. Whether you are replacing a key machine, buying your first truck, opening a practice, or trying to move forward after a financial setback, it can be worthwhile to explore equipment financing designed around more than one rigid score cutoff.
Why Do Rigid Bank Score Cutoffs Lead to Declines—and How Does Equipment Collateral Change the Picture?
Traditional banks often use narrow lending policies. A credit score, time in business, tax-return history, and existing relationship with the bank may all be filtered through fixed minimums. If one item falls outside the policy, the application may be declined quickly—even when the equipment would support a practical revenue-producing need.
Equipment financing evaluates a different kind of transaction. The asset being purchased may serve as collateral for the financing, which changes the risk picture compared with an unsecured loan. A commercial truck, dental equipment, manufacturing machine, or other eligible asset has identifiable value and a specific business purpose. That does not eliminate underwriting requirements, but it can give lenders another factor to consider alongside credit history.
This is why an equipment-financing conversation should begin with the complete picture: what you are buying, how it will be used, your experience in the industry, your business structure, available cash for a down payment if needed, and the overall strength of the file. The Funding Booth’s equipment financing options are meant to help applicants explore that broader picture rather than assume a single score tells the whole story.
Can You Finance Equipment After Bankruptcy Without Automatic Disqualification?
Past bankruptcy does not automatically mean every equipment-financing option is closed. Lenders may look at the type of bankruptcy, whether it has been discharged, how much time has passed, recent credit behavior, the equipment being financed, and the applicant’s current ability to support the payment.
There is no universal rule, and no responsible provider should promise approval. Still, a bankruptcy is a historical event—not the only information that matters. A business owner may have rebuilt payment habits, gained relevant industry experience, developed a viable operating plan, or identified equipment that directly supports revenue. Those facts can be meaningful in an underwriting review.
Being clear and accurate from the beginning is usually the best approach. If there was a past financial hardship, prepare a concise explanation if requested and be ready to show what has changed. For a helpful overview of how inquiries and credit review may fit into the process, visit The Funding Booth’s credit process.
What If You Have No Score, Thin Credit, or Only an ITIN?
A traditional credit profile is not available to every capable business owner. Some applicants have thin credit because they are new to borrowing. Others do not have an established score at all. ITIN-only applicants may also find that conventional bank processes do not fit their circumstances.
These situations can require more individualized review. Relevant factors may include the requested equipment, industry background, cash available, proof of identity and business formation, bank activity, customer contracts, or a qualified co-applicant when appropriate. The specific requirements depend on the program and the file.
The important point is that a missing or limited score is not necessarily the end of the conversation. It may mean the financing path, lender, down payment, or documentation needs to be different. The Funding Booth can help identify whether an equipment-focused option may be worth considering while keeping expectations realistic.
Can a Day-One Startup Finance Its First Truck or Dental Practice Equipment?
Startups often face a familiar challenge: they need equipment to begin earning revenue, but they do not yet have years of business financials to show. A transportation operator may need a first truck before taking on routes. A dentist may need chairs, imaging equipment, or other essential tools before opening a new practice. A contractor may need machinery to perform the work that will build a customer base.
Day-one financing may be possible for some applicants and equipment types, but startup files are evaluated carefully. Industry experience can matter. So can the quality and usefulness of the equipment, the size of the request, the applicant’s personal credit profile or alternative documentation, and the funds available for a potential down payment.
Some qualified applicants may have access to $0 down options. That does not mean $0 down is available to everyone or for every purchase. Eligibility depends on the lender’s review, the strength of the application, the equipment, and program guidelines. If a down payment is required, it can be helpful to view it as one potential way to make a file more financeable rather than as a judgment about the business idea.
Will Checking Options Affect Your Credit Score?
Exploring options through The Funding Booth uses a soft inquiry. A soft inquiry allows an initial review without the impact associated with a hard credit inquiry. That can offer welcome breathing room for business owners who are comparing possibilities or who have worked hard to rebuild their credit.
A lender may request additional authorization later in the process, depending on the program and the stage of review. The best practice is to ask what type of inquiry is being used and when, so you understand the process before moving forward. There is no obligation to accept an offer simply because you explored available options.
What Paperwork Should You Expect for Equipment Financing?
The answer depends on the file. For qualified established businesses with sufficient business history and credit, application-only approvals up to $500,000 are generally available. “Application-only” does not mean every applicant or every transaction will qualify with no further questions; it means that some stronger, established files may be reviewed without a full financial package.
Startup, challenged-credit, ITIN-only, or otherwise complex files may require more documentation. That can include equipment quotes, business bank statements, identification documents, business formation records, invoices, tax returns, financial statements, proof of relevant experience, or an explanation of how the equipment supports operations. More documentation is not automatically bad news. It often gives a lender the context needed to evaluate a file fairly.
For a closer look at why documentation levels vary, read Application-Only vs. Full Financial Package: What to Know.
How Quickly Can You Receive Equipment-Financing Numbers or a Decision?
For straightforward files, preliminary numbers may often be available the same day or the next business day. Decisions for straightforward files may also come within 24–48 hours. Actual timing can vary based on the lender, the completeness of the application, the amount requested, the type and condition of the equipment, and whether additional documentation is needed.
Complex or startup files may take longer because there are more details to review. Providing clear, complete information early can help avoid preventable delays, but no timeline should be treated as a guarantee. The goal is a thoughtful review and clear communication—not an unrealistic promise.
How Can You Strengthen an Equipment-Financing Application?
You do not need a perfect story to submit a stronger application. Start by confirming that the equipment quote is accurate and specific. Know the purchase price, vendor, model, condition, and intended use. Be prepared to explain how the asset will support revenue, efficiency, capacity, or reliability.
- Submit complete, consistent application information.
- Share relevant industry experience, especially for a startup or new business entity.
- Keep business and personal information current and easy to verify.
- Provide requested documents promptly and avoid altering or omitting important details.
- Consider whether a down payment, additional documentation, or a different equipment selection could improve available options.
- Ask about both new and used equipment. Used-equipment eligibility may be available without age limits, subject to lender and transaction review.
It is also reasonable to compare the service experience. The Funding Booth’s customer reviews can offer perspective from business owners who have gone through the process.
FAQ
Is there an upfront fee to explore equipment-financing options?
No. The Funding Booth does not charge upfront fees to explore options, and there is no obligation to proceed. Terms, fees, and payment details should be reviewed carefully if an offer is presented.
Can I finance used equipment?
Used equipment may be eligible, including equipment without age limits. Eligibility still depends on the asset, vendor, transaction details, and lender guidelines.
Can I qualify for equipment financing with challenged credit?
Possibly. Challenged credit does not guarantee approval, but some programs may consider factors beyond a score, including the equipment, business purpose, experience, available documentation, and overall application strength.
Do I need to be in business for years before applying?
Not always. Startup and day-one business opportunities may exist, including for purchases such as a first truck or equipment for a new dental practice. These files often need additional review and documentation.
Whether you have past bankruptcy, thin credit, an ITIN, no established score, or a brand-new business, The Funding Booth is here to help you explore the next practical step without judgment. Credit history is part of the story, not the end. You can begin with a one-page application or call (888) 551-0215 to discuss your equipment-financing options.